
Last updated: November 17, 2026
You were driving home on I-90 in a heavy Seattle rain when the steering suddenly went light. Your car slid across the lane and into the barrier, or into the car next to you. Now you’re on the shoulder with the hazards on, wondering if your insurance will pay for any of this.
Does insurance cover hydroplaning? Yes. A hydroplaning crash is covered like any other crash, by the coverage you bought. Collision pays for your car. Liability pays for damage and injuries you cause to others. PIP helps with your medical bills no matter who was at fault. The harder question is who was at fault.
The short answer: Your regular car insurance covers a hydroplaning crash. Collision fixes your car, liability pays others, and PIP helps with medical bills. Hydroplaning isn’t an excuse in Washington: drivers must slow down for wet roads. If another driver hydroplaned into you, their insurance should pay.
What is hydroplaning?
Hydroplaning happens when water builds up between your tires and the road. The tires lose their grip and skid, and the car can feel like it’s floating. Steering and braking stop working the way you expect. Washington’s Driver Guide says to slow down whenever the road is wet to prevent it.
That’s the Department of Licensing’s own description (Washington State Driver Guide, section 5.6).
Does insurance cover hydroplaning accidents?
Yes. There’s no special hydroplaning coverage, and you don’t need one. Your collision coverage pays to fix your car, minus your deductible. Your liability coverage pays for harm you cause to other people and their property. PIP pays medical bills for you and your passengers. If you skipped collision, you’ll pay for your own car.
| What happened | Your car | Your injuries | Others’ losses |
|---|---|---|---|
| You hydroplaned into a barrier or guardrail | Your collision coverage | Your PIP, then health insurance | Your property damage liability pays for the barrier |
| You hydroplaned into another car | Your collision coverage | Your PIP | Your liability coverage |
| Another driver hydroplaned into you | Their property damage liability, or your collision first | Their bodily injury liability, plus your PIP | Not your problem |
| That driver had little or no insurance | Your UIM property damage or collision | Your UIM and PIP | Not your problem |
Comprehensive coverage isn’t what pays here. In the Insurance Commissioner’s words, collision covers hitting another car or object, or flipping over. Comprehensive coverage is for things like theft, fire, vandalism, and hitting an animal.
Who is at fault for hydroplaning?
Washington law points at the driver who hydroplaned. It says your speed must be reasonable for the conditions, and controlled so you can avoid a crash. Rain doesn’t change that rule. It lowers the safe speed. A driver who hydroplaned at the speed limit in heavy rain can still be found careless for going too fast for the road.
The speed rule is RCW 46.61.400(1), which also requires drivers to slow down for special hazards. Breaking a traffic law is evidence of carelessness, not automatic proof (RCW 5.40.050). Other facts matter too, like worn tires, following too closely, or water pooled from a clogged drain.
What are the causes of hydroplaning?
Speed, water, and tires. Hydroplaning starts when water builds up between your tires and the road, so standing water and heavy rain set it up. Washington’s Driver Guide says slowing down on wet roads prevents it. It also warns that worn tires cause slipping and sliding on wet roads, and low tire pressure affects handling.
| Cause | What Washington’s rule or guide says |
|---|---|
| Speed | Drive no faster than is reasonable for the conditions, and slow down for special hazards (RCW 46.61.400) |
| Water on the road | Hydroplaning happens when water builds up between tires and road (Driver Guide 5.6) |
| Worn tires | Tread shouldn’t be less than 2/32 of an inch (Driver Guide 2.5) |
| Low tire pressure | It can affect handling (Driver Guide 2.5) |
| Following too closely | Not more closely than is reasonable and prudent (RCW 46.61.145) |
The tread and tire pressure guidance is in the Driver Guide, section 2.5. Following too closely is against the law (RCW 46.61.145).
How common are wet-road crashes?
Very common. Nationally, crashes on wet pavement average about 860,000 a year, based on 2019 to 2023 data. That’s 15% of all crashes and 70% of weather-related crashes. Wet-pavement crashes kill about 4,050 people a year. Snow and ice crashes are far fewer, as the chart shows.
U.S. crashes per year by road surface, 2019–2023 average
What if another driver hydroplaned into you?
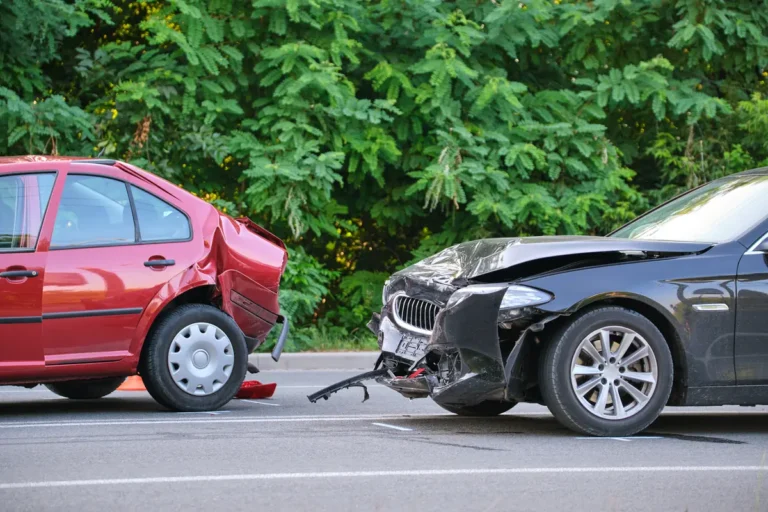
Then you claim against that driver’s insurance. A driver who loses control on a wet road and crosses into your lane or rear-ends you can be found at fault, because the speed rule applies to them. Their liability coverage pays for your car and injuries. Your own PIP can pay early medical bills while the claim moves.
If your insurer pays first, it must include your deductible when it collects from the other side (WAC 284-30-393). If you were partly at fault, your payment goes down by your share (RCW 4.22.005). You generally have three years to file a lawsuit (RCW 4.16.080).
What should you do if you hydroplane?
While it’s happening, take your foot off the gas and keep the wheel steady. With antilock brakes, brake gently. Without them, hard braking can make the skid worse. Look where you want to go and wait for the tires to grip. After a crash, get safe, call 911 if anyone’s hurt, and photograph the road.
- Ease off. Foot off the accelerator.
- Brake gently. Especially without antilock brakes.
- Hold steady. Don’t jerk the wheel.
- Get safe. Move out of traffic if no one is hurt.
- Photograph. Standing water, drains, skid marks, tires.
- Report it. Within four days if anyone was hurt or damage is $1,000+.
The steps during a skid are from the Driver Guide. The reporting rule is RCW 46.52.030. If you weren’t the one who hydroplaned, read who pays your car accident claim in Washington.
When we take a crash case, Rich handles it himself. He studied mechanical engineering before law, so he looks closely at speed, tires, and the road surface in a skid crash. Insurers pay more when they know a lawyer will go to court.
FAQ
Is hydroplaning an at-fault accident?
It can be, for the driver who hydroplaned. Washington expects you to slow down for a wet road, so rain alone isn’t an excuse. The same goes for darkness: see car accident at night.
Will my insurance rates go up after a hydroplaning accident?
They may. Insurers can use your driving record and the claims you’ve filed to set your rate, per the Insurance Commissioner.
Does comprehensive coverage pay for hydroplaning?
No. Hitting another car or an object is a collision claim. Comprehensive coverage is for things like theft, fire, vandalism, and animals.
Can bald tires make me more at fault?
They can be used against you. The Driver Guide says tread shouldn’t be less than 2/32 of an inch.
What does No Win, No Fee mean?
You pay nothing up front. Our fee comes out of the money we win for you. No hourly bills. No retainer. If we don’t win, you owe us nothing. Not even the case costs.
Talk to Rich about your wet-road crash
Does insurance cover hydroplaning? Yes, but the fight is usually over fault. If another driver slid into you, or an insurer is blaming the rain instead of the driver, you deserve someone who looks at the speed, the tires, and the road. Rich Martin has handled more than 2,000 injury cases in 28 years and taken more than 30 to a jury.
We help people hurt in crashes in Bellevue, Seattle, Tacoma, and across Washington. Your case review is free. No Win, No Fee. We speak English and Korean.
Call (425) 635-2000 or see how we handle car accident cases.
Keep reading
What Is a Bodily Injury Settlement? A Washington Guide
Last updated: November 13, 2026 The adjuster from the other driver’s insurance company calls back. They say your car claim is done, and now…
Do You Have to Wear a Seatbelt in the Back Seat in Washington?
Last updated: November 12, 2026 You slide into the back of a rideshare outside a Bellevue restaurant. The belt buckle is buried in the…
How Many Car Accidents Happen per Day?
Last updated: November 11, 2026 You just got rear-ended on your way home, and while you wait for the tow truck, you wonder how…